R&D TAX INCENTIVE COMPLIANCE & REVIEW SUPPORT
Strengthen your R&D Tax Incentive claim with clear evidence
HCPA helps businesses maintain the technical and financial documentation needed to support an R&D Tax Incentive claim and respond effectively if the claim is reviewed.
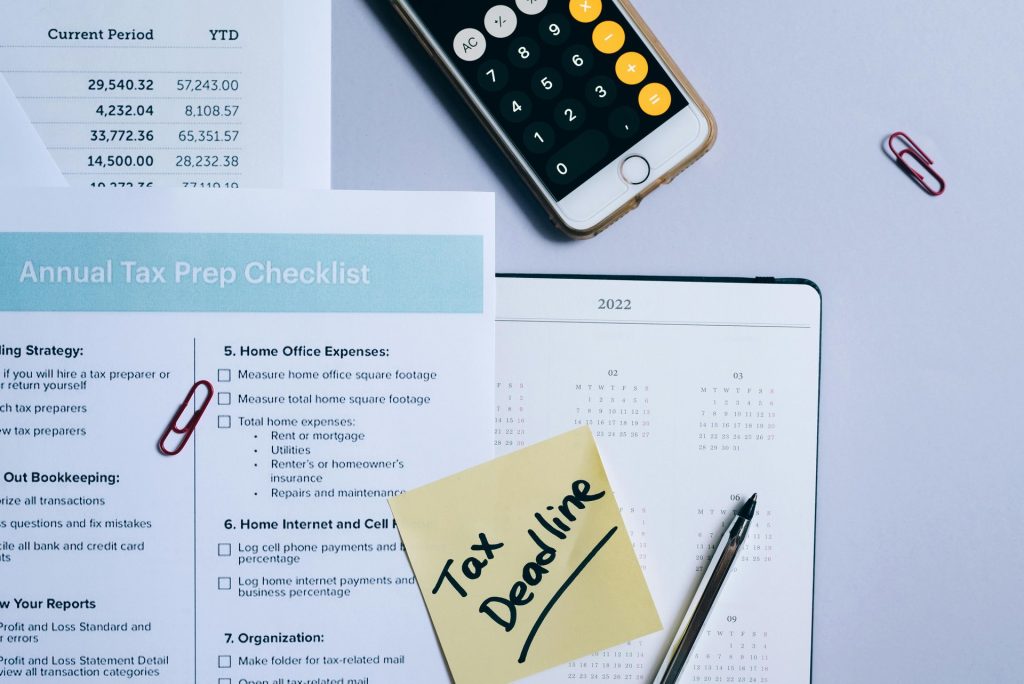
A strong R&DTI claim depends on more than preparing an application at the end of the financial year. Businesses need evidence showing what R&D was undertaken, how the activities progressed and how the claimed expenditure relates to that work.
The Department of Industry, Science and Resources can review the eligibility of the R&D activities included in the application, while the ATO may examine the expenditure claimed through the company tax return.
HCPA helps businesses bring the technical and financial evidence together, identify gaps and respond clearly where a claim is reviewed or questioned.
When R&D Tax Incentive compliance issues need immediate attention
Compliance gaps can become apparent while a claim is being prepared, during an internal review or when DISR or the ATO asks for supporting evidence. The first step is understanding what can be substantiated and where further work is needed.
Poor or incomplete R&D records
A business may have conducted genuine R&D but have limited evidence showing what was tested, how the work progressed or what technical uncertainty was being addressed. Reconstructing this after the event can make the claim harder to support.
Missing employee time records
Where staff work across R&D and non-R&D activities, poor time recording can make it difficult to calculate how much salary expenditure relates to the R&D work.
Questions about claimed expenditure
Not every project cost will necessarily form part of the R&D Tax Incentive calculation. Where costs have been incorrectly identified or apportioned, the financial side of the claim may need closer review.
DISR or ATO review
If DISR reviews the eligibility of the registered activities or the ATO examines the expenditure claimed, the business needs to bring together the technical and financial evidence supporting the claim.
Key R&D Tax Incentive compliance requirements
R&D Tax Incentive compliance starts while the work is happening. Strong claims are supported by records that connect the R&D activities, the people undertaking them and the expenditure being claimed.
Maintain contemporaneous R&D records
Records should be created as R&D activities are planned and conducted, rather than reconstructed when the application is being prepared.
Depending on the project, this may include project plans, test results, laboratory notes, development records, trial documentation or internal communications. The government recommends keeping records as activities and expenditure occur.
Connect records to the R&D activities
Documentation should do more than show that development work occurred.
Records should demonstrate what was being investigated, what activities were undertaken, when they occurred and how they connect to the R&D described in the application.
Support the R&D expenditure calculation
Financial records should show how the expenditure being claimed relates to the R&D activities.
General ledger entries, invoices, payroll records and supporting calculations should provide a clear basis for the costs included and any apportionment used.
Record employee time spent on R&D
Where employees divide their time between R&D and other work, businesses need a reliable basis for determining how much time relates to eligible activities.
In HCPA’s experience, weak time records can make salary and wage expenditure harder to substantiate, particularly where staff move regularly between R&D and non-R&D work.
Keep the supporting evidence organised
Technical and financial records need to remain available after the application and tax return have been submitted.
A clear claim file should connect the activities in the application with the technical evidence, expenditure calculations and underlying financial records.
Check the claim before submission
Before submission, check that the technical application, expenditure calculation and supporting evidence are consistent.
This can identify gaps or discrepancies before the claim is lodged and make later questions from DISR or the ATO easier to address.
Preparing for an R&D Tax Incentive review
Registration of R&D activities does not remove the need to substantiate the claim later.
DISR may review whether the activities included in the application satisfy the R&D Tax Incentive requirements, while the ATO may examine whether the expenditure claimed is properly supported.
Businesses should therefore be able to produce evidence such as:
project plans and technical records
laboratory notes, test results or trial documentation
software development records such as Jira or Confluence
emails and internal project communications
employee time records
profit and loss statements and general ledgers
invoices and supporting financial documents
calculations showing how R&D expenditure was determined
The important point is consistency. The activities described in the application, the project evidence and the expenditure calculation should support the same account of what R&D was undertaken.
If gaps are identified, establish which parts of the claim are well supported and where additional explanation may be required before responding.
HCPA can review the records behind your claim, identify gaps and help prepare a clear response to questions raised by DISR or the ATO.
Speak with an HCPA R&D Tax Incentive consultantWhat to do if your R&D Tax Incentive claim is reviewed
Understand what is being reviewed
Confirm whether the questions relate to the R&D activities, the expenditure claimed or both.
Gather the supporting records
Bring together the technical, employee and financial evidence relevant to the specific areas being reviewed.
Check the claim against the evidence
Confirm that the activities and expenditure described in the claim can be supported by the available records.
Prepare a clear response
Answer the questions directly and connect each response to the evidence that supports it.
Why choose HCPA for R&D Tax Incentive compliance?
HCPA combines technical R&D assessment with financial review, helping businesses strengthen both the activity evidence and expenditure calculations behind their claims.
An HCPA R&D Tax Incentive consultant can review project documentation, assess expenditure evidence, identify gaps and support businesses responding to DISR or ATO reviews.
businesses supported
industry consultants
billion in client revenue
HCPA can also review a claim before submission to identify inconsistencies between the application, supporting evidence and expenditure calculation. This can make the eventual application easier to substantiate and reduce the need to reconstruct evidence after the R&D work has been completed.
Frequently asked questions about R&D Tax Incentive compliance
What records and supporting documents must a business maintain to meet R&D Tax Incentive compliance requirements?
You need evidence supporting both the R&D activities and the expenditure being claimed.
Technical evidence may include project plans, test results, laboratory notes, development records, emails or trial documentation. Financial evidence can include general ledger entries, invoices, payroll records and calculations supporting the expenditure claimed.
The government’s R&D Tax Incentive record-keeping guidance provides examples of records that can support both activities and expenditure.
How can a business prepare for a DISR review or ATO audit of its R&D Tax Incentive claim?
Start by bringing together the records that support the part of the claim being reviewed.
DISR may examine the eligibility of the R&D activities, while the ATO may review the expenditure claimed. Your application, technical records and financial calculations should therefore support each other.
The application, technical evidence and financial calculations should align, and the response should address the specific questions raised rather than simply providing documents in bulk.
HCPA can review the available evidence and help prepare responses to the specific questions raised.
What does contemporaneous documentation mean for an R&D Tax Incentive claim?
It means maintaining records while the R&D is being planned and conducted rather than recreating them at the end of the financial year.
These records can show what was being investigated, what work occurred and how the project changed as testing or experimentation progressed.
Current record-keeping guidance for the R&DTI recommends creating records at the time the activities and expenditure occur.
Do we need to track staff time spent on R&D?
Where employees divide their time between R&D and other work, time records can be important for calculating the salary and wage expenditure attributable to R&D activities.
The records should provide a reasonable basis for the apportionment used rather than relying on unsupported estimates prepared later.
What happens if we have conducted genuine R&D but have poor documentation?
Genuine technical work still needs to be supported by evidence.
Start by identifying what contemporaneous evidence is available across project records, technical systems, communications and financial information.
An R&D Tax Incentive consultant can review that evidence, identify gaps and help establish what can be substantiated.
What does the ATO review in an R&D Tax Incentive claim?
The ATO may examine the expenditure included in the R&D Tax Incentive claim.
Businesses should be able to explain how the expenditure was calculated, how it relates to the R&D activities and how costs such as employee salaries were apportioned where only part of the work related to R&D.
Can DISR review the R&D activities after registration?
Yes. Registration does not prevent DISR from examining whether the activities satisfy the R&D Tax Incentive requirements.
Businesses should therefore continue maintaining the technical evidence behind their registered activities.
The government’s guidance on R&DTI application decisions explains how examinations and findings can apply to registered activities.
What if the expenditure calculation does not match the technical records?
Review both sides of the claim before submission or before responding to DISR or the ATO.
The expenditure should be traceable to the activities being claimed. If the records and calculation do not align, identify whether the issue sits in the activity description, cost allocation, apportionment or supporting evidence.
Can HCPA help if we have already received questions from DISR or the ATO?
Yes.
HCPA can review the questions raised, assess the technical and financial evidence available and help prepare a response addressing the areas under review.
The appropriate response will depend on the evidence available and the specific activities or expenditure being examined.
Related R&D Tax Incentive resources
Preparing your R&D Tax Incentive claim
Undertaking R&D and need to understand what may be eligible?
Managing R&D Tax Incentive compliance
Need stronger records or support with a DISR or ATO review?